How Do Stablecoins Work?
Understanding how do stablecoins work is essential for anyone entering the digital asset space, as these instruments bridge the gap between traditional finance and blockchain technology. Unlike volatile cryptocurrencies that fluctuate wildly based on market sentiment, stablecoins are engineered to maintain a steady price, typically pegged to a stable asset like the US dollar.
By examining their diverse mechanisms—from fiat collateralization to algorithmic stabilization—you will gain a clear picture of how these tokens provide a reliable store of value. Whether you are looking to facilitate cross-border payments or simply hold a digital version of cash, learning the mechanics behind these assets is a vital first step in your financial journey.
The Core Mechanism of Price Stability
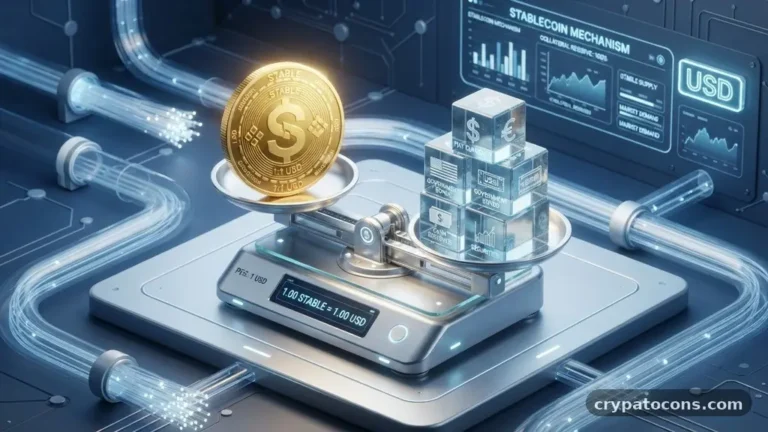
At the most fundamental level, the question of how do stablecoins work centers on their ability to maintain a consistent value, usually at a 1:1 ratio with a fiat currency. To achieve this, issuers utilize different backing strategies that act as a tether, keeping the token price from drifting away from its target. Think of this as a digital anchor that prevents the asset from floating freely in the volatile crypto market.
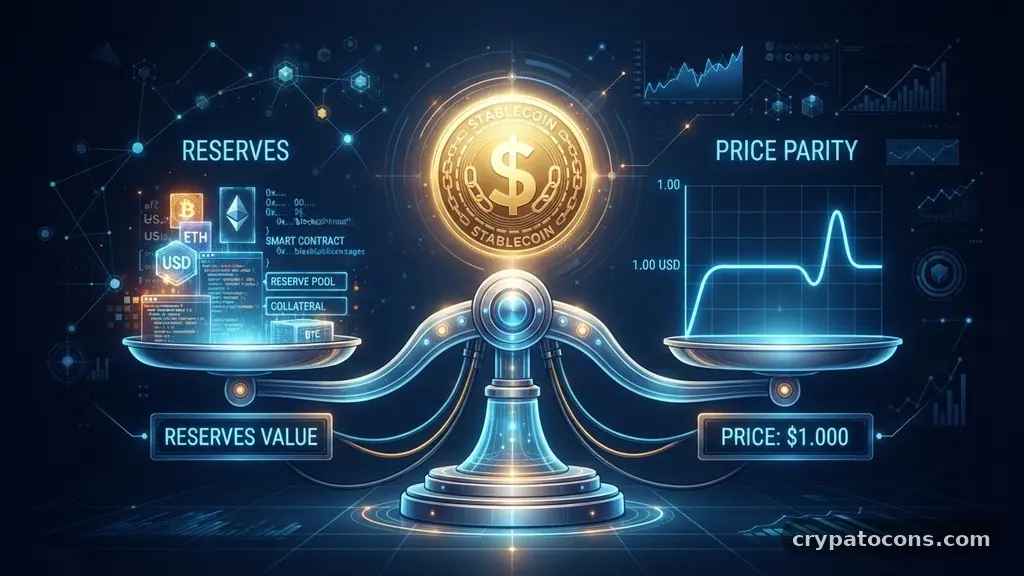
Most stablecoins achieve this through collateralization, where the issuer holds a reserve of assets equivalent to the number of tokens in circulation. If a company issues 100 million tokens, they must theoretically hold 100 million dollars in a bank account or equivalent liquid investments. When users want to redeem their tokens, they send them back to the issuer, who burns the tokens and releases the corresponding fiat currency from the reserve.
This redemption process is the heartbeat of the system, ensuring that the market price remains close to the peg. If the price of the stablecoin rises slightly above $1.00, arbitrageurs can buy the asset for $1.00 from the issuer and sell it on the open market for a profit, which naturally brings the price back down. Conversely, if the price dips below $1.00, traders can buy the cheap tokens and redeem them for the full dollar value, creating demand that pushes the price back up.
Fiat-Collateralized Stablecoins
Fiat-backed tokens are the most common variety, representing a direct claim on traditional money held in institutional accounts. You can think of these as digital receipts for cash, where each token is a representation of a dollar held in a secure, audited vault. Major players like USDC or USDT utilize this model to provide users with a familiar, stable interface for their digital transactions.
The strength of this model lies in its simplicity and direct correlation with the global banking system. Because the reserves are held in cash or high-quality cash equivalents like short-term treasury bills, the risk of extreme volatility is significantly reduced. However, this also means the system is centralized, as users must trust the issuer to maintain honest reserves and remain solvent.
Transparency is a major factor for these issuers, who often publish monthly attestations or audits to prove their holdings match the supply. You should always look for these reports if you are considering holding large amounts of a specific stablecoin. By verifying that the reserves exist, you confirm that your digital holdings are truly backed by tangible assets that remain under the control of the issuing entity.
Crypto-Collateralized Assets
Some stablecoins take a different route by using other cryptocurrencies as collateral rather than traditional bank-held dollars. This approach is designed to be more decentralized, as it removes the need for a central bank or a single corporate entity to hold the reserves. Instead, the process is governed by smart contracts on a blockchain, which automatically manage the collateral levels.
Because cryptocurrencies like Ethereum or Bitcoin are themselves volatile, these systems must be over-collateralized to remain stable. For example, you might need to deposit $150 worth of Ethereum to mint $100 worth of a stablecoin. This buffer ensures that even if the underlying collateral drops in value, the stablecoin remains fully backed by the remaining assets.
If the value of the collateral falls below a certain threshold, the system triggers a liquidation process to protect the stability of the stablecoin. This automated mechanism is a fascinating application of decentralized finance, as it replaces human intermediaries with immutable code. While this removes the need for a traditional bank, it does require users to understand the risk of liquidation and the technical complexities of managing decentralized positions.
Algorithmic and Seigniorage Models
Algorithmic stablecoins represent the most experimental category, as they do not rely on a 1:1 reserve of assets to maintain their value. Instead, they function more like a central bank, using algorithms to manage the supply of tokens based on demand. When the price rises above the target, the protocol issues more tokens; when it falls, it removes them from circulation to create scarcity.
These systems rely heavily on market incentives to keep the price stable. They often use a multi-token structure, where a secondary “governance” or “share” token absorbs the volatility of the system. If the stablecoin loses its peg, the protocol incentivizes users to burn the stablecoin in exchange for these secondary tokens, theoretically restoring the balance through market demand.
This model is inherently high-risk, as it depends entirely on the continued belief and participation of the network participants. If confidence in the algorithm falters, it can lead to a “death spiral” where the value of the stablecoin collapses rapidly. While these systems offer a vision of a truly autonomous currency, they have faced significant challenges in real-world market conditions, often proving to be less resilient than their collateralized counterparts.
The Role of Reserves and Audits
The integrity of a stablecoin project depends almost entirely on the quality and transparency of its reserves. For fiat-backed assets, this means holding high-liquidity investments that can be converted to cash quickly during periods of market stress. You will often see issuers holding a mix of cash, bank deposits, and short-term government bonds to ensure they can meet redemption requests at any time.
Regular audits are the standard by which these companies prove their legitimacy to the public. An independent accounting firm reviews the issuer’s books to verify that the amount of fiat held matches the number of tokens issued on the blockchain. Without these audits, users are essentially taking the issuer’s word that the reserves are sufficient, which is a major point of concern for risk-averse investors.
It is important to understand that an “attestation” is not the same as a full, exhaustive audit. An attestation is a snapshot of the reserves at a specific moment in time, whereas an audit is a more comprehensive look at the financial health and internal controls of the company.
When you research a stablecoin, check if they provide regular, detailed reports from reputable accounting firms like those listed by the U.S. Securities and Exchange Commission for financial transparency standards.
Comparison of Stablecoin Architectures
To help visualize how these different models stack up, the following table summarizes the primary characteristics of the three main stablecoin types. Each architecture offers a different balance of decentralization, capital efficiency, and systemic risk.
| Stablecoin Type | Collateral Method | Primary Risk Factor | Decentralization Level |
|---|---|---|---|
| Fiat-Backed | USD, Treasuries | Centralized failure/freeze | Low |
| Crypto-Backed | ETH, BTC, etc. | Collateral value drop | High |
| Algorithmic | Code-based supply | Protocol collapse/loss of faith | Very High |
Each of these categories serves a different purpose in the digital ecosystem. Fiat-backed coins are primarily used for trading and payments, while crypto-backed and algorithmic coins are often favored by DeFi enthusiasts who want to avoid traditional banking systems entirely. Understanding these distinctions allows you to choose the type of stablecoin that aligns with your personal risk tolerance and financial goals.
Common Use Cases for Digital Stability
Why do people use stablecoins instead of just holding regular US dollars in a bank account? The answer lies in the speed, accessibility, and utility that blockchain technology provides. Stablecoins allow you to move value across borders in minutes rather than days, and they operate 24/7 without the need for traditional banking hours or international wire transfer delays.
Many traders use these assets as a “parking spot” for their capital during periods of extreme crypto market volatility. Instead of converting their crypto back to fiat and paying heavy fees or waiting for bank processing times, they can simply swap their volatile coins for a stablecoin within the same ecosystem. This keeps their money liquid and ready to deploy as soon as they see a new opportunity.
Stablecoins are also increasingly used for global payments and remittances. By using a stablecoin, a person in one country can send value to someone in another country with minimal transaction costs and near-instant settlement. This is particularly transformative for regions where traditional banking infrastructure is expensive, slow, or inaccessible to the general population.
- Faster Settlement: Transactions occur in minutes, regardless of the sender’s or receiver’s location.
- 24/7 Availability: Unlike banks, blockchain networks never close, allowing for constant access to funds.
- Lower Fees: Blockchain transaction costs are often a fraction of traditional international wire transfer fees.
- Programmability: Stablecoins can be integrated into smart contracts, enabling automated escrow and lending services.
- Global Accessibility: Anyone with a smartphone and internet access can hold and use these digital assets.
Frequently Asked Questions
How do stablecoins make money for their issuers?
Issuers typically earn revenue through interest earned on the reserve assets. If an issuer holds billions in US Treasury bills, the yield generated from those bonds represents a significant income stream. Some issuers also charge small fees for minting or redeeming large amounts of tokens, which helps cover operational costs.
Are stablecoins safe to hold long-term?
While they are designed to be stable, they are not risk-free. Their safety depends on the issuer’s transparency, the quality of their reserves, and the regulatory environment in which they operate. You should conduct your own due diligence on the specific stablecoin you choose and consider the risks of centralized custody.
What happens if a stablecoin loses its peg?
If a stablecoin loses its peg, it is often called “de-pegging.” This usually happens due to a loss of market confidence, a failure in the reserves, or an algorithmic error. When this occurs, the market price can drop significantly below $1.00, and holders may face difficulty redeeming their tokens for the expected value.
Is there a difference between a stablecoin and a CBDC?
Yes, there is a major difference. A Central Bank Digital Currency (CBDC) is a digital form of a country’s sovereign currency, issued and regulated by the central bank itself. A stablecoin is a private-sector asset issued by a company or a decentralized protocol, usually pegged to a fiat currency like the dollar.
Can I earn interest on my stablecoins?
Yes, many decentralized finance (DeFi) platforms and centralized crypto exchanges allow you to earn yield on your stablecoin holdings. By lending your assets to liquidity pools, you can earn interest payments, which are often higher than traditional bank savings accounts. However, this comes with the added risk of smart contract exploits or platform insolvency.
Conclusion
Learning how do stablecoins work provides a window into the evolution of money itself. By combining the stability of traditional fiat currencies with the technical efficiency of blockchain, these assets have become a cornerstone of the modern digital economy. Whether you are seeking a way to protect your gains during a market downturn or looking for a more efficient way to handle global payments, stablecoins offer a versatile toolset for your financial toolkit.
As you explore this space, remember that the technology is still maturing and that transparency remains your best safeguard. Always prioritize well-audited, highly liquid assets and stay informed about the evolving regulatory landscape. By taking a thoughtful and cautious approach, you can effectively use stablecoins to manage your digital wealth and participate in the rapidly expanding world of decentralized finance.