What Is a Stablecoin?: A Practical Guide?
Understanding what is a stablecoin is essential for anyone looking to bridge the gap between traditional finance and the rapidly evolving world of digital assets. These tokens are designed to maintain a steady price, usually by pegging their value to a stable reserve asset like the U.S. dollar.
By minimizing the volatility typically associated with cryptocurrencies, they serve as a practical tool for traders, businesses, and everyday users. This article explores how these digital instruments function, why they hold such a prominent place in the market, and how they provide a reliable way to manage value in a decentralized ecosystem.
Defining the Core Mechanics
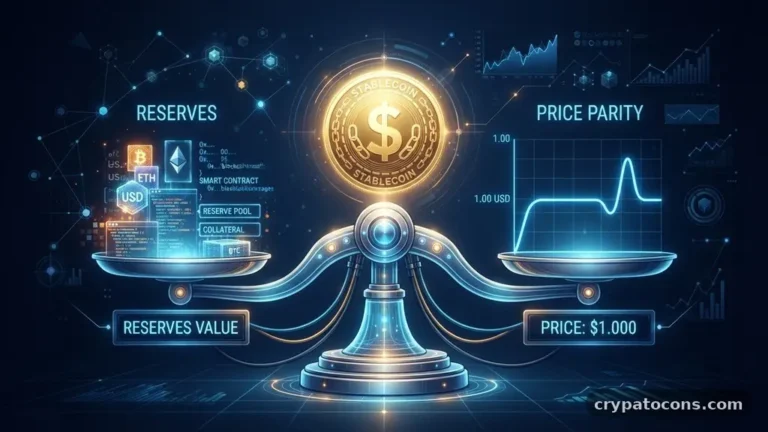
At its simplest level, a stablecoin is a type of cryptocurrency that ties its value to an external reference, such as a fiat currency or a commodity. While Bitcoin or Ethereum might swing by double-digit percentages in a single day, these assets aim for price consistency. This stability is achieved through various backing mechanisms that ensure the token remains worth approximately $1.00.
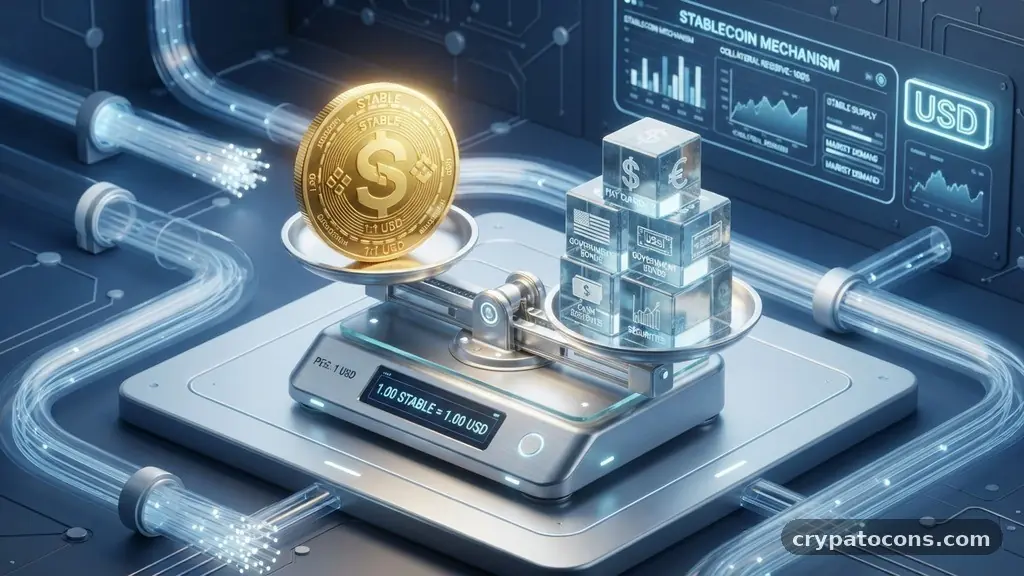
Most stablecoins operate by holding reserves that match the number of tokens in circulation. If a company issues 100 million tokens, it theoretically keeps $100 million in a bank account or in high-quality, short-term government debt. This 1:1 ratio allows users to redeem their digital tokens for the underlying asset, which anchors the market price.
Without this peg, the digital currency market would be far more difficult to navigate for institutional participants. They provide a “safe harbor” during periods of extreme market turbulence. When a trader wants to exit a volatile position, they often move their funds into a stablecoin to preserve their purchasing power without needing to convert back to traditional banking systems.
Common Types of Backing
Not all stablecoins are built the same way, and their stability depends heavily on how they maintain their peg. The most common variety is the fiat-collateralized model, which relies on centralized entities to hold cash or cash equivalents. You can think of these as digital IOUs that are backed by actual money held in a vault or account.
Another category is crypto-collateralized, where the backing is another digital asset. Because the underlying crypto is also volatile, these systems use over-collateralization to protect the peg. A protocol might require you to deposit $150 worth of Ethereum to mint $100 worth of its native stablecoin, providing a buffer against price drops.
Algorithmic models represent a third, more experimental approach. Instead of physical reserves, they use smart contracts to adjust the supply of the coin based on market demand. If the price rises above the peg, the protocol creates more tokens; if it falls below, it burns tokens to reduce supply and drive the price back up.
| Type | Backing Mechanism | Primary Risk |
|---|---|---|
| Fiat-Backed | Cash, Treasury Bills | Centralization, Auditing |
| Crypto-Backed | Other Cryptocurrencies | Liquidation risk, Volatility |
| Algorithmic | Code-based supply control | Systemic failure, De-pegging |
The Role of USDT and USDC
Two names dominate the current landscape: USDT (Tether) and USDC (USD Coin). USDT is the oldest and most widely used token in the sector, serving as the primary liquidity source for most crypto exchanges. Because it is available on nearly every platform, it acts as the “de facto” dollar of the digital asset world.
USDC, managed by Circle, has gained significant traction by focusing on transparency and regulatory compliance. It is often preferred by institutional investors and decentralized finance (DeFi) platforms that require rigorous proof of reserves. The competition between these two providers has driven improvements in how issuers report their holdings.
Both tokens are used extensively for payments and cross-border transfers. Because they exist on blockchain networks, they can be sent anywhere in the world in minutes, regardless of the time of day or weekend bank closures. This efficiency makes them a popular alternative to the traditional SWIFT network for international settlements.
Why Use Stablecoins Instead of Cash?
The primary advantage of using a stablecoin is the ability to interact with decentralized applications without leaving the blockchain. When you hold money in a standard bank, you are subject to the bank’s operating hours and international transfer delays. A digital token moves instantly across borders, 24/7, with minimal fees.
Furthermore, these assets allow users to earn interest on their holdings. Many DeFi protocols offer yield-bearing accounts where you can deposit your tokens and receive rewards for providing liquidity. This is often more accessible than setting up a high-yield savings account at a traditional financial institution.
For developers and merchants, they offer a consistent unit of account. Accepting payments in a volatile asset like Bitcoin is risky, as the value could drop before the merchant converts it to cash. By accepting a stable asset, the business knows exactly how much revenue it is receiving, simplifying accounting and financial planning.
Key Risks and Considerations
While they are useful, stablecoins are not without risk. The biggest concern is the quality of the reserve assets held by the issuer. If a company claims to hold $1 billion in cash but actually holds risky debt instruments, the peg could collapse if investors lose confidence and attempt to withdraw their funds simultaneously.
Regulatory uncertainty is another major factor. Governments worldwide are looking closely at how these assets are issued and managed. New laws could restrict how issuers operate or require them to maintain stricter capital requirements, which would change the economics of the entire sector.
Smart contract risk also plays a significant role, particularly for decentralized or algorithmic versions. If a bug exists in the code that governs the supply or the collateralization, hackers could exploit it to drain the reserves. For those interested in the technical standards, the Federal Reserve provides ongoing research regarding the implications of these digital assets on the broader economy.
How They Impact Global Finance
Stablecoins have the potential to democratize access to the U.S. dollar for populations living in countries with high inflation. In regions where the local currency loses value rapidly, citizens can hold a digital dollar-pegged asset to protect their savings. This provides a level of financial stability that was previously unavailable to the average person.
They also facilitate faster and cheaper remittances. Sending money home to family members through traditional channels can cost 5-10% in fees and take several days. Using a stablecoin, the sender can move the funds for a fraction of the cost, ensuring that more money reaches the intended recipient.
The integration of these tokens into existing payment systems is accelerating. Major payment processors are beginning to support blockchain-based settlements, which could eventually make the underlying technology invisible to the average consumer. In this vision of the future, people would use stablecoins to pay for groceries or rent without even realizing they are interacting with a blockchain.
Common Use Cases for Investors
* Trading Liquidity: Providing a stable base for buying and selling volatile assets on exchanges.
* DeFi Yield Farming: Earning interest by lending assets to decentralized lending protocols.
* Cross-Border Payments: Sending funds globally without traditional banking intermediaries.
* Inflation Hedge: Protecting purchasing power in economies with unstable local currencies.
* Portfolio Rebalancing: Quickly moving between assets to capture market opportunities.
Frequently Asked Questions
Is a stablecoin the same as Bitcoin?
No, they are fundamentally different. Bitcoin is a decentralized asset with a price that fluctuates based on supply and demand, while a stablecoin is designed to maintain a fixed value relative to a stable asset like the U.S. dollar.
What happens if a stablecoin loses its peg?
If a token loses its peg, it is referred to as “de-pegging.” This means the market price has fallen below or risen above the intended value, often signaling a loss of trust in the issuer’s ability to redeem the tokens for the underlying collateral.
Can I lose money holding a stablecoin?
Yes, you can lose money if the issuer becomes insolvent or if the underlying collateral is devalued. While they are designed to be stable, they are not guaranteed by the FDIC or any government entity like a traditional bank account.
Are stablecoins regulated?
Regulations vary by jurisdiction and are currently evolving. In many places, issuers are increasingly required to provide regular audits of their reserves and comply with anti-money laundering (AML) laws.
Who creates stablecoins?
They are created by private companies, decentralized organizations, or protocols. Some are backed by centralized firms like Circle or Tether, while others are managed by autonomous code known as smart contracts.
Summary of Future Outlook
The future of the digital economy will likely be built on the foundation of stable value. As these instruments become more regulated and transparent, their utility will expand beyond crypto traders to include mainstream consumers and large-scale enterprises. The ability to move value as easily as sending an email is a powerful shift in the way we interact with money.
While you should remain cautious about the specific risks associated with different backing models, it is clear that they have become a permanent feature of the modern financial landscape. Staying informed about the issuer’s transparency and the underlying technology will help you make better decisions. As the market matures, keep an eye on how central bank digital currencies might eventually compete with or complement the private stablecoins we use today.